Your Dashboard Is Your Credit Score: How E-Commerce Sellers Are Unlocking Capital From Platform Data
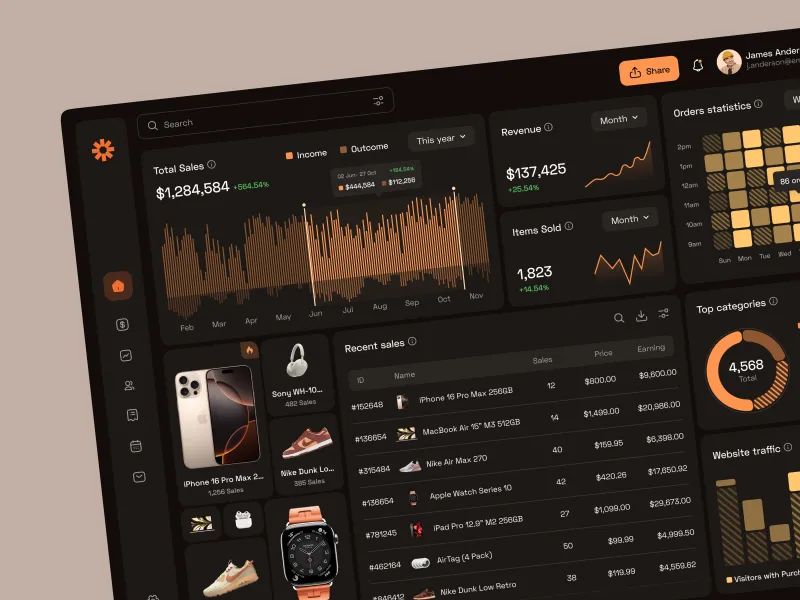
Photo: ecommerce seller laptop analytics dashboard online store, via cdn.dribbble.com
For most of American commercial history, a small business asking for capital had to make a case through proxies: tax returns, personal credit scores, collateral documents. The problem was always that these proxies described the business poorly. A seller doing $2 million on Shopify with 40% repeat purchase rates looked, on paper, identical to a seller doing $2 million with no customer loyalty at all.
That era is ending. Direct-to-consumer platforms have become the underwriting layer themselves, and the data flowing through them — payment volumes, inventory turns, retention cohorts — is now the primary evidence lenders and investors use to size up an e-commerce operator. If you sell online, your dashboard has quietly become your credit file.
What Underwriters Actually Pull From Your Platforms
When a financing provider connects to a seller's stack, here is what they typically extract and why it matters:
- Gross merchandise volume and payment velocity from Shopify or Stripe — not just the total, but its trend and volatility. Flat-and-steady revenue underwrites better than spiky-and-larger.
- Inventory turnover — how quickly stock converts to sales. Slow turns suggest capital trapped in a warehouse; fast turns suggest a business that can deploy an inventory loan productively.
- Customer retention and repeat purchase rate — the single strongest signal of durable revenue. A 35% repeat rate reads like recurring revenue to an underwriter.
- Contribution margin after ad spend — lenders know that top-line growth funded by Meta ads at breakeven economics is not financeable growth.
- Chargeback and refund rates — a high refund rate is treated like a small business version of a delinquency flag.
- Concentration risk — for Amazon sellers, the share of revenue dependent on a single marketplace or a single SKU.
Notice what is absent from that list: the owner's FICO score, the years in operation, the value of the founder's home. Platform-era underwriting evaluates the business as a machine, not the founder as a borrower.
Embedded Financing: The Capital That Lives Inside Your Tools
The most significant shift is structural. Financing no longer requires a trip to the bank; it arrives inside the software sellers already use. Shopify offers cash advances and term loans directly within its merchant dashboard, sized against sales history. Amazon provides inventory and revenue-based offers to sellers meeting performance thresholds. Stripe Connect has become the plumbing through which dozens of embedded lenders underwrite merchants they have never met in person.
The embedded model has real advantages. Underwriting is fast — often minutes rather than weeks — because the platform already holds the data. Offers scale with sales, so a growing store sees growing limits. Repayment is frequently collected as a fixed percentage of daily sales, which flexes naturally with revenue instead of demanding the same payment in a slow month.
It also has trade-offs founders should weigh honestly. Embedded advances can carry effective annualized costs well above traditional bank debt, and because repayment is frictionless, it is easy to stack multiple advances until daily deductions strangle cash flow. The convenience that makes embedded capital easy to access also makes it easy to overuse. Treat it as a tool for specific, high-return uses — a proven inventory buy ahead of peak season, a purchase order you can fulfill profitably — not as a general-purpose cushion.
Building a Capital-Ready Operations Stack
The sellers who command the best terms treat financing-readiness as an operations discipline. Four practices matter most:
Keep your books connected and clean. Underwriters reconcile platform data against accounting software. A Shopify store whose revenue does not match its QuickBooks file invites either a down-sized offer or a declined one. Use a proper accounting integration, not manual spreadsheets.
Track cohort retention deliberately. Most sellers know their total repeat rate; few can show retention by acquisition cohort. A simple cohort table demonstrating that customers acquired in Q1 are still buying in Q4 is among the most persuasive exhibits a seller can put in front of a capital partner.
Know your unit economics cold. Be able to state your contribution margin per order after product cost, fulfillment, and advertising — and defend it. Lenders size offers against the margin, not the revenue.
Avoid stacking advances carelessly. Every embedded advance files a UCC lien or takes a position on receivables. Before taking a second or third advance, map what is already pledged and what daily repayment load the business can absorb in its weakest month, not its strongest.
From Dashboard to Diligence
The trajectory points further than advances. Sellers with strong platform metrics are increasingly graduating into revenue-based financing with longer terms, inventory-backed credit lines from specialized lenders, and in select cases venture debt from funds that now underwrite DTC brands on cohort data rather than projections. The same metrics that unlock a Shopify advance today are the ones a growth-stage investor will diligence tomorrow.
The practical takeaway: your platform data is already being evaluated whether you curate it or not. Build the stack, keep the numbers reconciled, and understand the cost of every dollar before the daily deductions begin. In e-commerce finance, the founders who win are the ones who treat their dashboards not as reporting tools, but as their balance sheet's most persuasive advocate.